#capex
4 articles
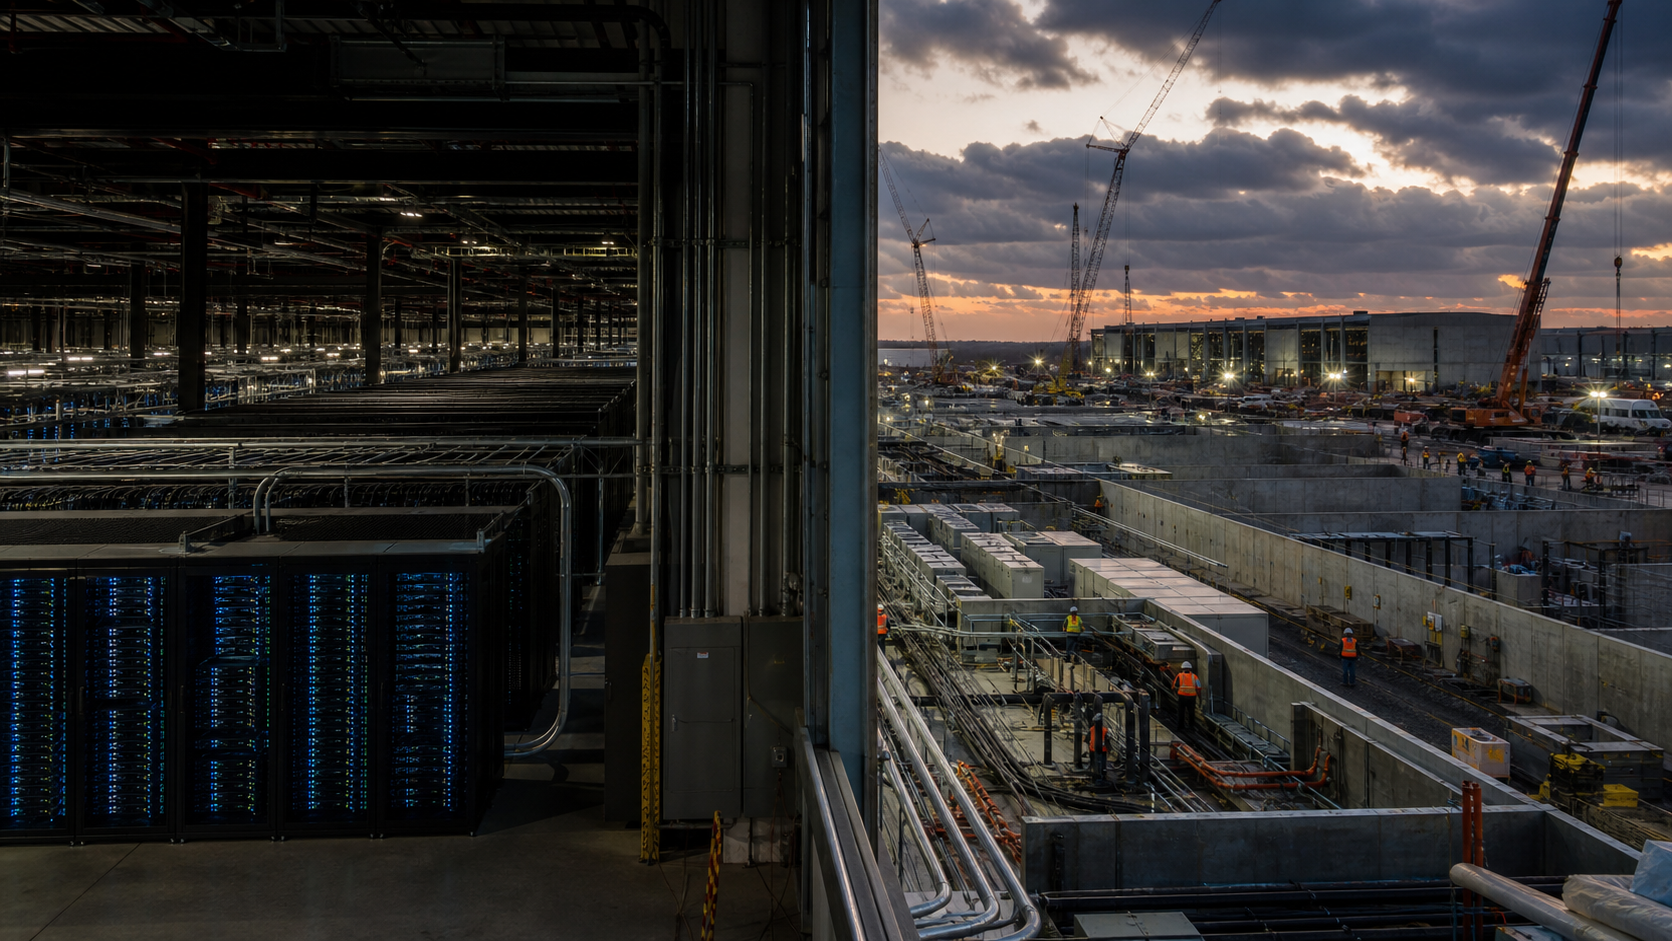
AI’s Infrastructure Bet Has an Expiration Date
The defining risk in AI infrastructure is not whether demand exists, but whether today’s expensive, tightly coupled facilities remain economically useful as chips, models, and workloads change. Optionality is becoming a core datacenter product.
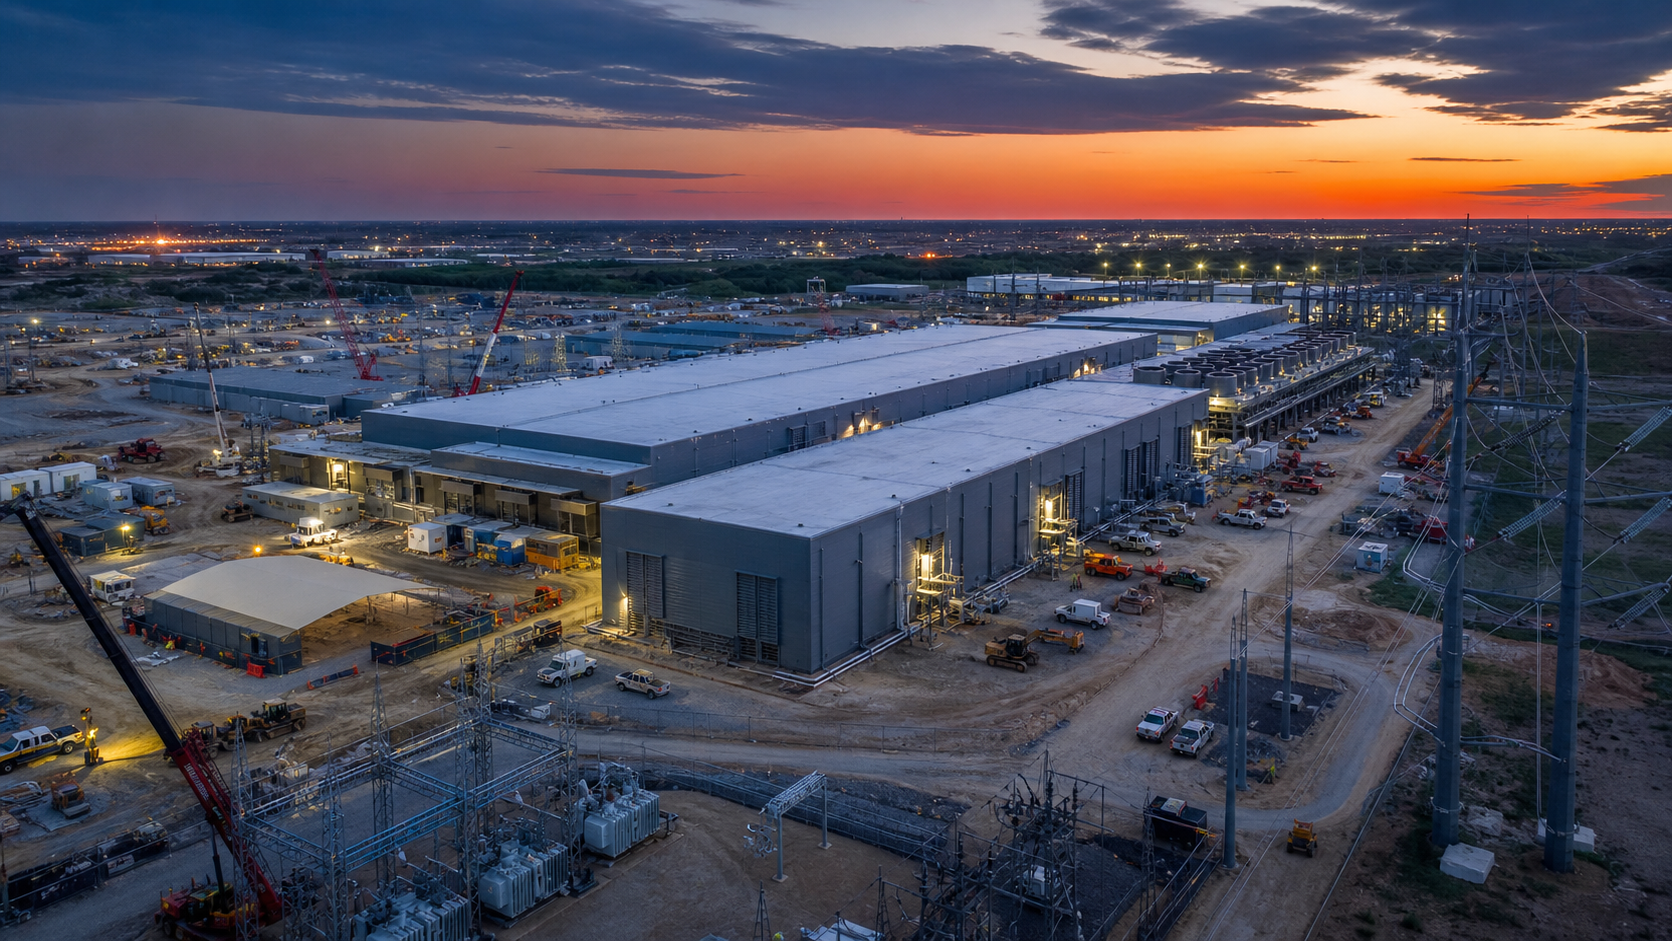
The New AI Arms Race Runs Through Power, Debt, and Concrete
The AI industry still likes to narrate itself as a software race. Increasingly, it behaves like a collision between cloud computing, utility planning, construction logistics, and corporate finance.
The AI Boom Is Becoming an Infrastructure Business
AI still gets discussed like a software category, but the economics are drifting toward energy, construction, procurement, and finance. That shift will shape who can compete far more than another season of model demos.
AI’s Real Business Model Is Starting to Look More Like Utilities Than Software
The market still loves to talk about AI as a software story: faster coding, smarter search, automated support. Beneath that layer, the more consequential shift is capital-heavy, physical, and geopolitical. AI is becoming a contest over who can finance and operate infrastructure at industrial scale.