#datacenters
41 articles · page 4 of 5
The AI Race Is No Longer About Models Alone. It Is About Balance Sheets.
The industry still talks as if progress is mainly a contest of algorithms. Increasingly, the decisive advantage comes from who can finance, site, power, and operationalize intelligence at industrial scale.
The AI Race Is No Longer About Models Alone. It Is About Balance Sheets.
The industry still talks as if progress is mainly a contest of algorithms. Increasingly, the decisive advantage comes from who can finance, site, power, and operationalize intelligence at industrial scale.
The AI Race Is No Longer About Models Alone. It Is About Balance Sheets.
The industry still talks as if progress is mainly a contest of algorithms. Increasingly, the decisive advantage comes from who can finance, site, power, and operationalize intelligence at industrial scale.
The New AI Arms Race Runs Through Power, Debt, and Concrete
The AI industry still likes to narrate itself as a software race. Increasingly, it behaves like a collision between cloud computing, utility planning, construction logistics, and corporate finance.
The New AI Moat Is a Utility Queue
By late August 2026, the public conversation about AI still fixates on models and demos. The harder truth is that power contracts, interconnection timelines, and capital structure are deciding more of the market than most product discourse admits.
AI's Real Scarcity Is Grid Access
The loudest AI race is about models, but the quieter one is about electricity, permits, and industrial coordination. The next durable advantage in AI will belong to the companies that can turn capital and power contracts into usable computing capacity.
AI Is Becoming an Infrastructure Business With a Software Front End
The industry still talks as if model intelligence alone decides the winners. Increasingly, the harder contest is over power, cooling, utilization, and the financial discipline required to turn compute into a product.
The AI Boom Is Becoming an Infrastructure Business
AI still gets discussed like a software category, but the economics are drifting toward energy, construction, procurement, and finance. That shift will shape who can compete far more than another season of model demos.
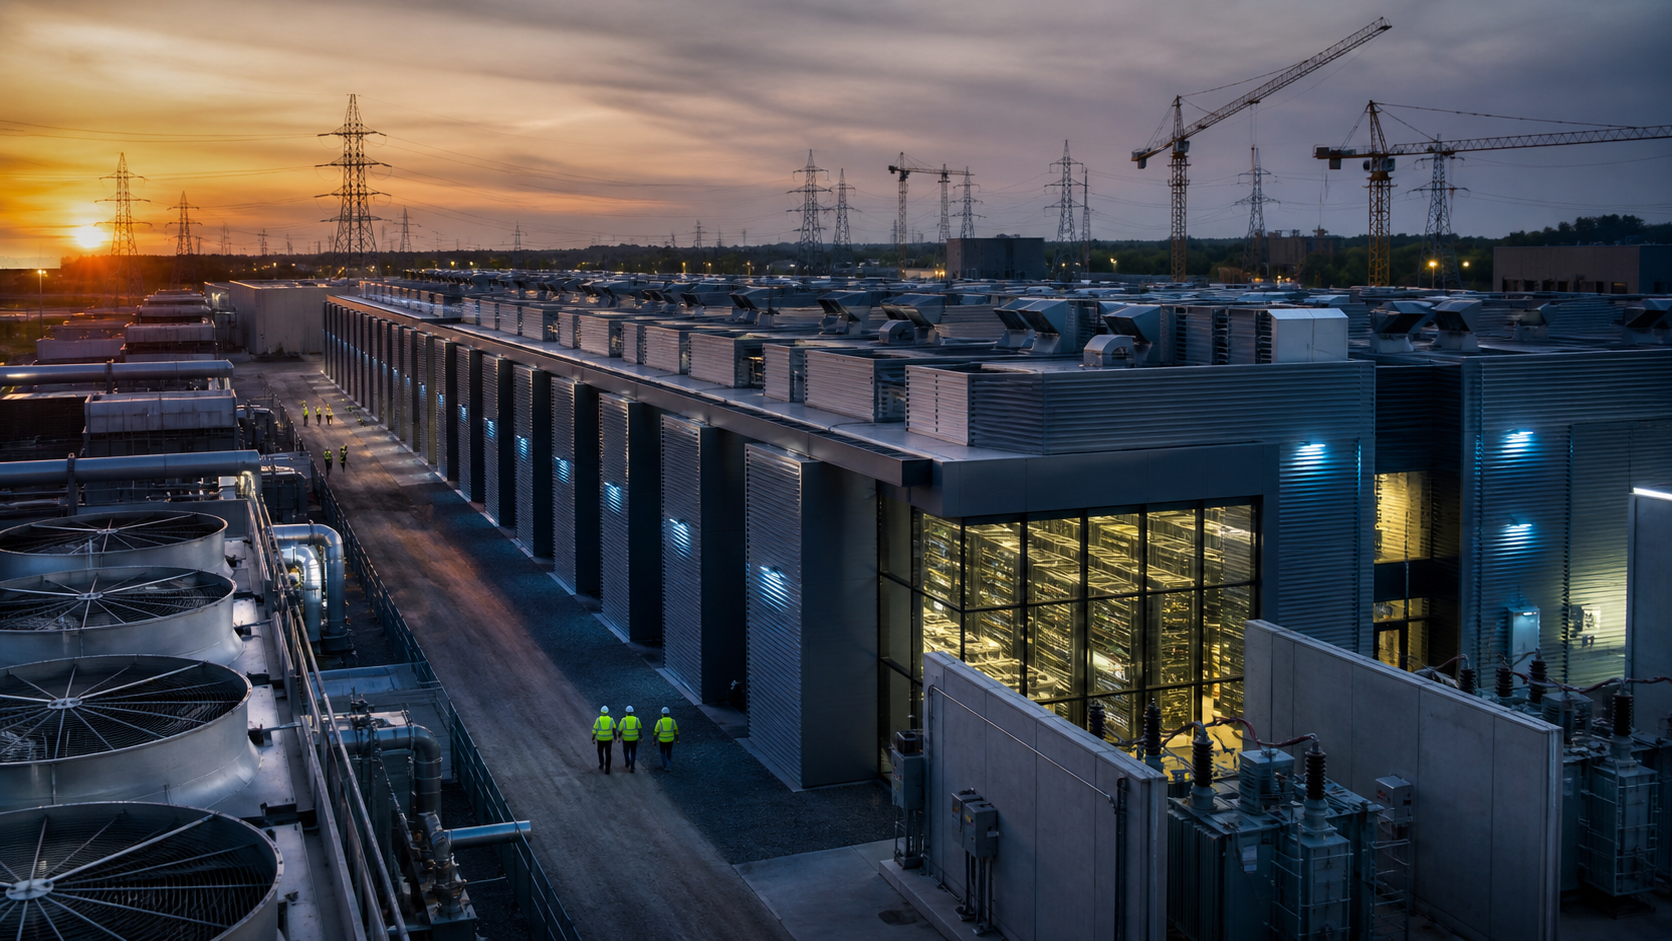
AI Infrastructure Has Left the Cloud Abstraction Layer
The industry spent years talking about AI as if it were just another software category. The money now moving into power, cooling, land, and grid access says otherwise: AI has become an infrastructure business with a software veneer.