Industry & Business
47 articles · page 3 of 6
AI Infrastructure Is Becoming a Balance-Sheet Product
The defining AI business decision is shifting from model access to capacity design. Power contracts, utilization, depreciation, and software efficiency now shape product strategy as directly as model quality does.
AI’s Next Margin Battle Will Be Fought in Concrete, Copper, and Contracts
The economics of AI are leaving the tidy world of software gross margins and entering the slower world of power, construction, and long-lived capital. That shift will reward companies that treat infrastructure commitments as product strategy, not background capacity planning.
AI’s New Balance Sheet Is Made of Concrete, Copper, and Power Contracts
The AI industry increasingly behaves less like software and more like heavy infrastructure. That shift changes who can compete, where margins hide, and which risks investors routinely underestimate.
AI’s Capital Cycle Is Starting to Look More Like Energy Infrastructure Than Software
The defining AI business decisions are moving from API pricing pages to substations, cooling systems, debt structures, and utilization forecasts. That shift changes who can compete—and how failure will arrive.
AI’s Most Expensive Bet Is Not the Model. It Is Idle Capacity.
The infrastructure race is usually framed as a contest to secure more compute. The harder business problem is deciding how much irreversible capacity to build before demand, hardware, and model economics change again.
AI’s Profit Margin Will Be Decided in the Queue
The decisive economics of generative AI are moving from model training to the less glamorous machinery of serving requests. Utilization, latency promises, and workload scheduling will separate durable products from expensive demonstrations.
The AI Infrastructure Winner Will Be the One That Wastes the Least
The defining business metric for AI compute will not be how many accelerators a company owns. It will be how much valuable work it extracts from every constrained megawatt and depreciating machine.
AI’s Software Margins Are Becoming an Infrastructure Accounting Problem
The AI market is sold with software language but increasingly built with utility-scale assets. Competitive advantage will depend as much on utilization, depreciation, and workload placement as on model quality.
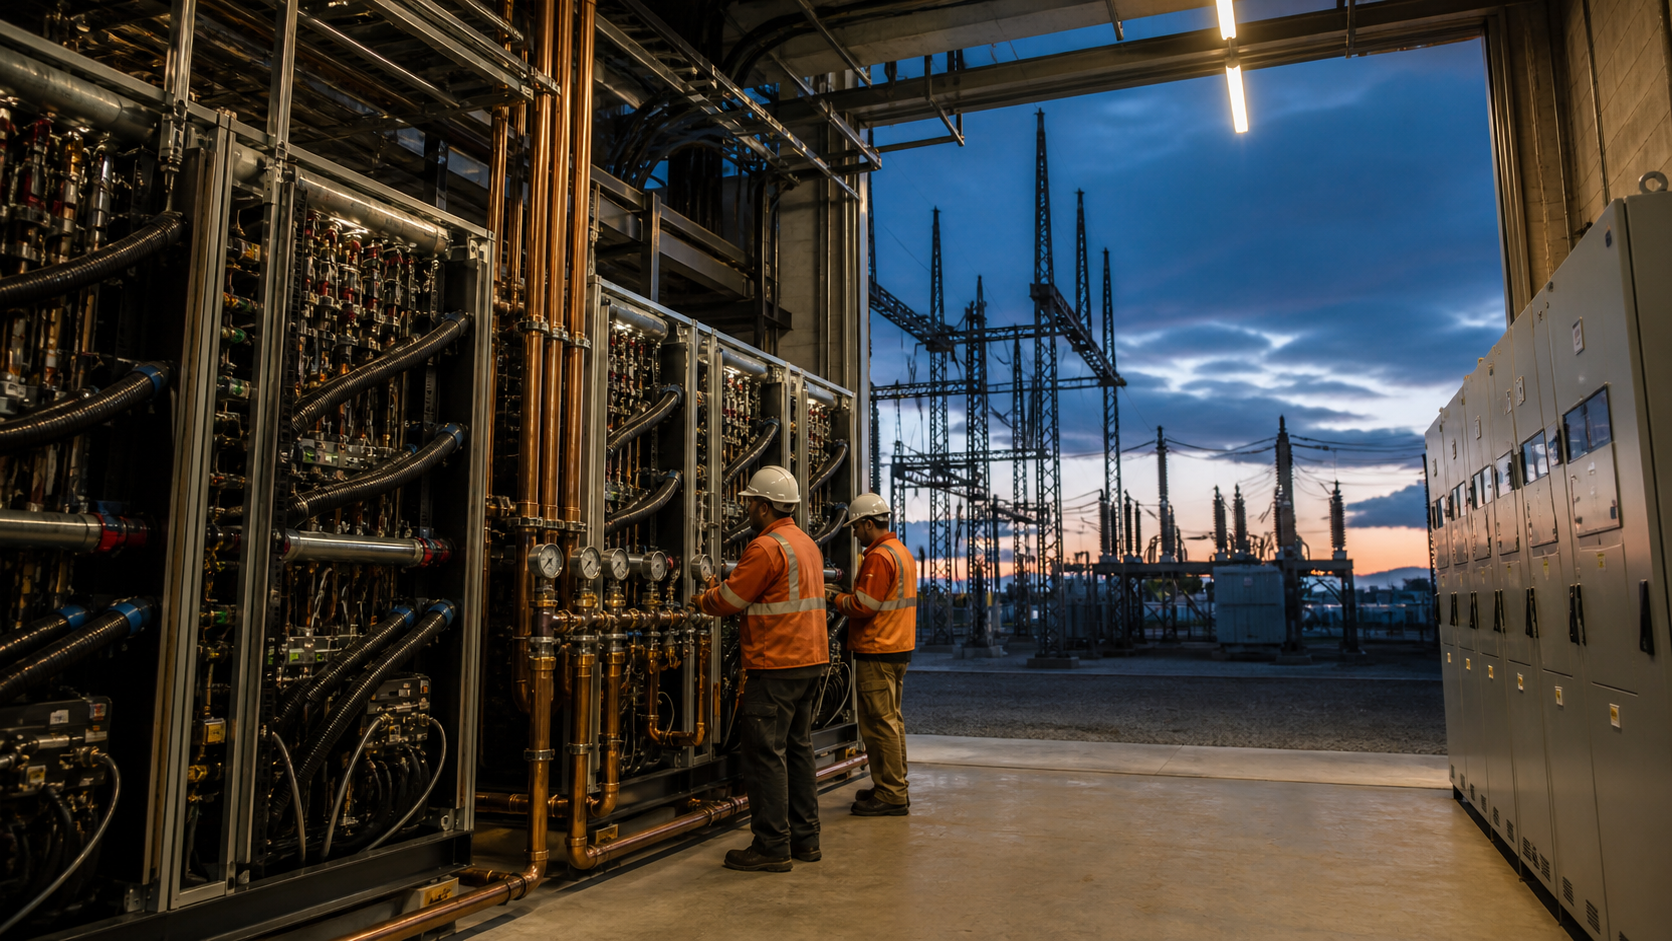
The Winning AI Cloud Will Run More Like a Utility Than a Chip Warehouse
As inference becomes the dominant recurring workload, accelerator ownership stops being the decisive advantage. Power contracts, queue design, cooling and utilization will determine who can sell dependable intelligence at a margin.